
A research-led look at Staysure’s single-trip, annual multi-trip and cruise policies, including where medical screening and policy detail shape the decision.
Travel insurance is easier to assess when the policy structure matches the holiday you actually plan to take. Staysure’s Ireland store puts three recognisable routes in front of travellers: cover for one trip, cover for several trips, and a cruise policy with additional cruise-related considerations.
We reviewed the Ireland product information rather than testing or buying a policy. The practical question is whether those routes make the decision clearer, and where a traveller still needs to slow down and read the terms.
Disclosure: this post includes affiliate links, and we may be paid a commission on purchases made through them.
→ Check current Staysure travel insurance options
The short version
- Single Trip Travel Insurance is the straightforward route for one defined holiday; Staysure says cancellation cover begins when the policy is bought.
- Annual Multi-Trip Travel Insurance may suit people taking several holidays, subject to eligibility and trip-duration rules.
- Cruise Travel Insurance addresses cruise-specific disruptions, with examples including missed port departures and cabin confinement.
- Staysure says it can consider most pre-existing medical conditions after screening, but cover depends on accurate disclosure and the policy issued.
Cover architecture
The three-route structure has a useful basic logic. For a one-off break, our review starts with Staysure Single Trip Travel Insurance; for repeat travel, compare Staysure Annual Multi-Trip Travel Insurance. Cruise travellers can also open Staysure Cruise Travel Insurance as a separate point of reference. The Single Trip Travel Insurance page describes protection for one holiday, from purchase until the return home, and says cancellation cover starts from purchase. That can be a sensible fit when the dates and destination are set and there is no reason to pay for an annual structure. Review the single-trip policy details alongside the quote, including cancellation conditions and the policy excess.
For travellers expecting several breaks, the Annual Multi-Trip Travel Insurance route packages multiple holidays into a policy year. Staysure’s page sets trip-duration and eligibility conditions, so the word “annual” should not be read as unlimited time away. Check the applicable limit for the traveller’s age and whether any extension is available before choosing. The annual multi-trip terms should be checked against every planned departure, not just the first holiday.
The third option, Cruise Travel Insurance, has a more specific job. Staysure describes it for river and ocean cruises and highlights cover considerations tied to the itinerary, including missed ports and cabin confinement. It is the clearest route to examine when a voyage is the main trip, rather than assuming a standard policy automatically handles every cruise disruption. Read Staysure cruise cover information beside the standard single-trip option if this is a one-off sailing.
Those are meaningful distinctions, but they do not settle the choice by themselves. The best starting point is the shape of the travel year, then the activities and health details that may change the policy fit.
→ Compare Staysure cover routes
Health disclosure
Medical underwriting is a central strength of the proposition for travellers who need to disclose an existing condition. Staysure says it can cover most pre-existing medical conditions, subject to screening and policy terms. Its Ireland site also describes emergency medical care and repatriation, with a round-the-clock emergency assistance service.
That is a useful invitation to get a quote rather than an automatic promise of acceptance. Screening answers, medical history, treatment status and the exact policy wording can all affect what is covered. A condition needs to be declared as requested; a reassuring headline cannot replace checking the final documents for exclusions, excesses, limits and any conditions attached to a claim.
We would treat this part as a decision checkpoint. Before paying, confirm that each traveller has answered the screening questions fully, that the proposed cover reflects the medical information supplied and that the policy documents describe the protection expected. This applies whether comparing one-trip cover, annual multi-trip cover or cruise insurance. If an answer is unclear, ask Staysure to explain it before purchase and keep the response with the travel records.
- List the conditions and relevant medical details requested during the quote.
- Check whether the final offer includes the condition and any related restrictions.
- Read emergency assistance instructions and know how to contact the helpline while away.
The strength here is a visible route for discussing medical needs. The limitation is equally important: “most conditions” is not every condition in every circumstance, and screening alone is not a guarantee that a particular claim will be paid.
→ Review Staysure medical cover information
Cruise claim scenarios
Cruise cover earns a separate place in the range because a ship itinerary creates scenarios that ordinary holiday language can miss. Staysure’s cruise information points to missed port departures, unused excursions and cabin confinement among the events relevant to cruise cover. Read the cruise policy page and the cruise cover details before comparing it with annual multi-trip cover. It also describes support for emergency treatment on board or in a hospital abroad.
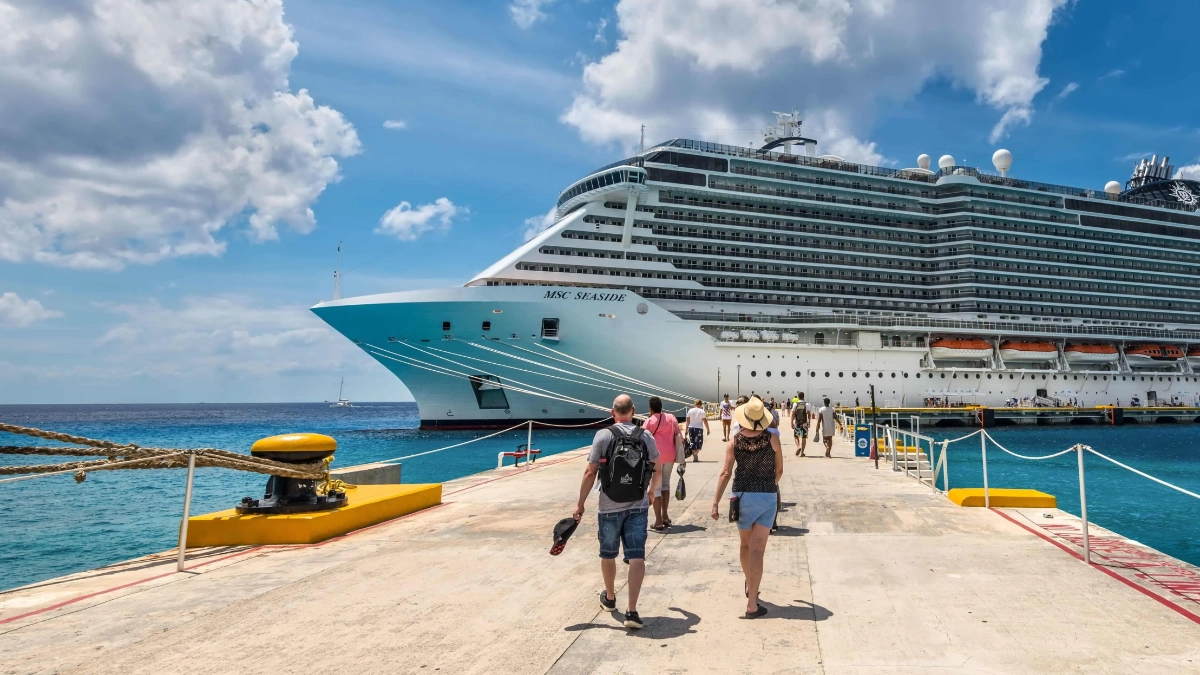
Travellers should compare the policy wording with their actual booking: how missed departure is defined, what evidence is needed, which prepaid costs qualify and whether an excursion must be arranged through the cruise operator. Confirm how the cover responds if a port is skipped or a traveller is confined to the cabin. These specifics matter more than the label “cruise” alone.
People taking a cruise as one of several holidays may also want to compare a cruise add-on or cruise-specific route against the annual option. The pages make both single-trip and annual formats available for cruises, but the right combination depends on trip frequency and the terms attached to each quote. Compare cruise cover with annual multi-trip cover and single-trip cover for the itinerary in hand.
The same principle applies to activities such as skiing or kayaking: read whether the activity is included, excluded or requires an extra. Staysure’s broader range includes winter sports cover, so active travellers should identify the relevant page and verify the exact activity and conditions before relying on a general travel policy.
→ Check Staysure cruise cover details
Quote variables
There is no universal route and no honest way to call one route best for everyone without seeing the quote and personal details. Cost will be shaped by factors such as destination, trip length, traveller details, medical screening and selected extras. The online quote is where those inputs become a specific offer, and readers should compare the final terms as carefully as the premium. Start the comparison with Single Trip Travel Insurance, Annual Multi-Trip Travel Insurance and Cruise Travel Insurance in the Ireland store.
Staysure’s information is strongest when it explains the broad structure and specialist cases. The trade-off is that buyers must assemble a decision from separate pages and detailed policy documents. This is normal for insurance, but it places the burden on the customer to check definitions and exclusions rather than taking a headline benefit at face value.
Our practical shortlist is simple:
- Choose the single-trip route as the first comparison for one planned holiday.
- Compare annual multi-trip when several journeys are likely, then check each trip’s permitted duration.
- Start with cruise cover when sailing is central to the holiday and scrutinise the cruise-specific benefits.
- In every case, disclose medical details and review exclusions, limits and excesses in the issued documents.
Before you decide
Can Staysure cover existing medical conditions?
Staysure says it can consider most pre-existing conditions after medical screening. Eligibility and cover depend on the information provided and the terms in the final policy, so check the quote and documents carefully.
Is annual cover automatically better for frequent travellers?
It can be more convenient for several trips, but trip-duration and eligibility rules apply. Compare those conditions with the full itinerary before deciding that an annual policy fits.
Does cruise insurance cover every missed port or excursion?
Staysure highlights cruise-related benefits, but the definitions and qualifying circumstances are set by the policy. Read the cruise wording for the specific disruption and costs you want covered.
Our take
Staysure is worth considering for Irish travellers who want a recognisable choice between one-off, annual and cruise-focused cover, particularly if medical screening is an important part of the search. Its strongest feature is the range of routes and the explicit attention to medical and cruise needs.
Our reservation is that product labels do not answer the important questions: personal eligibility, exclusions, trip limits and the final cost all emerge through the quote and policy wording. Start with the route that matches the itinerary, then check every condition that could affect a claim.